Builders Risk Insurance in Ontario
Insurance for new home construction, major renovations and residential building projects across Ontario.
Car Insurance That Fits Your Drive
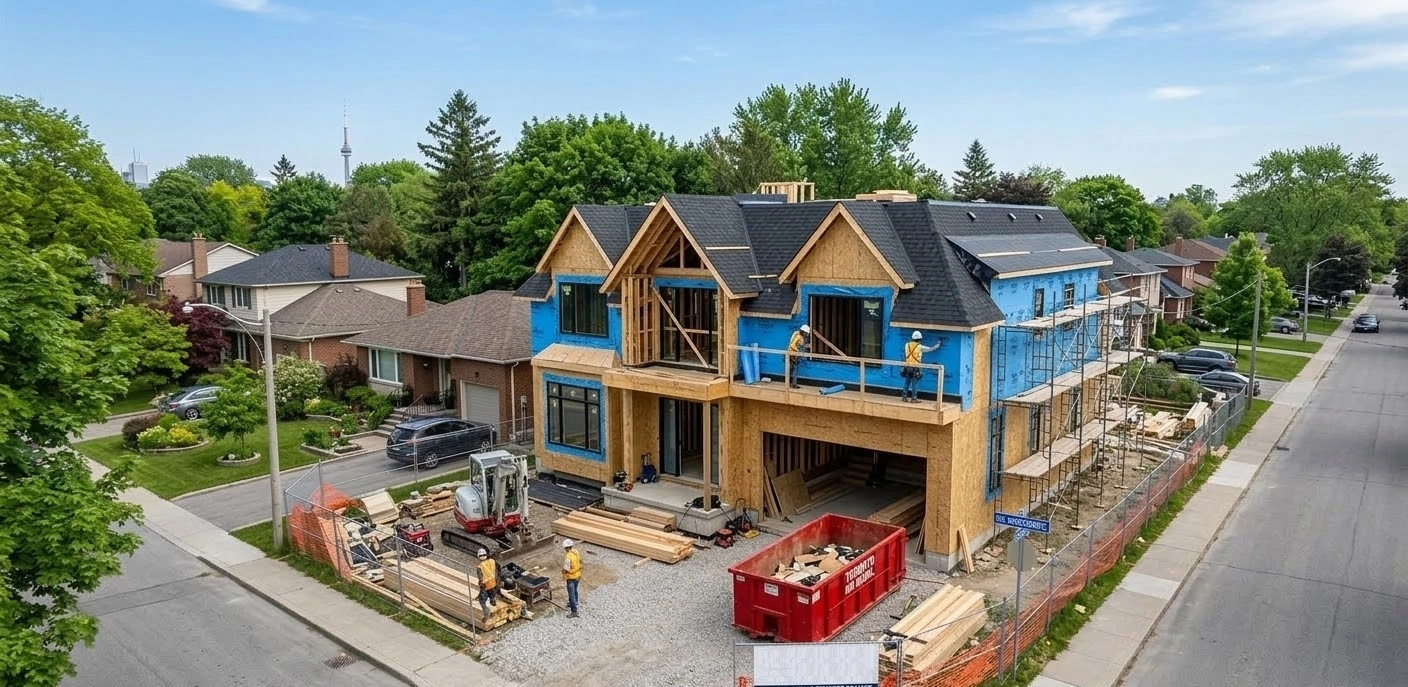
A property under construction has different insurance needs than a completed home. Builders risk insurance is designed for the construction period, whether you're building a new home, completing a major renovation or developing an investment property.
Humberview Insurance Brokers can help you find coverage that fits your project, construction value and timeline.
Builders Risk Insurance Coverage Options
| Hard Costs | Soft Costs | Existing Structure |
|---|---|---|
| Coverage for construction materials and labour | Coverage for additional expenses caused by a covered project delay | Protection for the existing building during renovations |
| Materials On & Off Site | Premises Liability | Wrap-Up Liability |
| Coverage for construction materials stored on or off site | Liability protection related to property ownership during construction | Project-specific liability coverage for multiple parties involved in construction |
Coverage availability varies by insurer, project and eligibility. Coverage is subject to policy terms, conditions, limits and exclusions. Premises liability and wrap-up liability may require separate coverage or policies.
Types of Builders Risk Insurance We Can Help With
Why Humberview for Builders Risk Insurance?
-
One Dedicated Broker
Work with the same licensed broker throughout your project.
-
Multiple Insurance Markets
Compare builders risk options from multiple insurers.
-
Clear, Simple Advice
Coverage structured around your project, construction value and timeline.
-
Independent Since 1982
Helping Ontario property owners protect what they build for over 40 years.
Builders Risk Insurance Prices 2026
The cost of builders risk insurance in Ontario can vary depending on factors such as the construction value, who is doing the work, the scope of the project, and how long the construction will take. Below are a few recent builders risk insurance examples we arranged for projects across Ontario, but every situation is unique and the best way to know your cost is to request a builders risk insurance quote.
| Builders Risk Project | Cost in 2026 |
|---|---|
| Large Toronto project with over $1.8M rebuild cost (12-month term) | $9,210 |
| Laneway house under construction for student housing (student rental policy required upon completion) | $2,700 |
| Etobicoke home with over $1.1M rebuild cost (12-month term) | $5,747 |
| Small cabin cottage under construction in Northern Ontario ($300,000 rebuild cost) | $2,314 |
| Cottage in Collingwood under construction with over $1M rebuild cost (12-month term) | $5,462 |
Builders Risk Insurance FAQ
-
What is builders risk insurance?
Builders risk insurance (also called course of construction insurance) is a specialized policy designed to protect a property while it is being built or undergoing major renovations. It typically provides coverage for the structure and construction materials against risks such as fire, theft, vandalism, and some times certain types of water damage during the construction process.
-
Who needs builders risk insurance in Ontario?
Builders risk insurance is commonly required for homeowners, investors, and developers who are building a new home or completing major renovations. In many cases, lenders may also require proof of builders risk insurance before construction begins.
-
Why can't a standard homeowners insurance policy cover a home under construction?
Standard homeowners insurance policies are designed for completed and occupied homes. When a property is under construction or undergoing major renovations, the risk profile changes significantly. Because of this, many insurers will either endorse the policy if possible or you may be required to get a different policy for the whole property until the project is completed and the home transitions back to a standard home policy.
-
What does builders risk insurance typically cover?
A builders risk policy may provide coverage for:
- The structure as its being built.
- Construction materials stored on site
- Materials waiting to be installed
- Damage caused by fire, theft, vandalism, or certain weather events
- Limited liability exposures related to the construction project
Coverage details can vary depending on the insurer and the scope of the project. Each coverage has a specific maximum or limit.
-
How is builders risk insurance different from a standard homeowners policy?
Builders risk insurance is structured very differently than a homeowners policy. For example:
- Liability is usually premises liability, which is more limited than the personal liability found in a homeowners policy.
- Builders risk policies typically do not include contents coverage.
- Additional Living Expenses (ALE) are not covered.
- Coverage is focused primarily on protecting the structure and construction materials, rather than the occupants and their personal belongings.
There are many considerations that property owners must take into account.
-
Does builders risk insurance cover water damage?
Water coverage under builders risk policies is often limited. Many builders risk policies do not cover overland water or surface water flooding. However, some policies may provide coverage for events such as sewer backup or flooding from a nearby body of water, depending on the insurer and policy wording.
-
Are builders risk insurance policies strict?
Yes. Builders risk policies are typically much stricter than standard homeowners insurance policies. Insurers closely review the scope of construction, who is completing the work, and other factors before offering coverage. Because the risks during construction are higher, underwriting guidelines tend to be more restrictive.
-
What are warranties in a builders risk insurance policy?
Builders risk policies often include policy warranties, which are specific conditions that must be followed in order for coverage to remain valid. Examples may include requirements related to site security, verifying each contractor has their own insurance policy, requirements and precautions when hot work or work with flame occurs, among others. Failure to comply with these warranties can void coverage during a claim.
-
How long does builders risk insurance last?
Builders risk policies are usually issued for a specific construction period, often between 6 and 12 months. If construction takes longer than expected, the policy may need to be extended until the project is complete. Some companies have limits on how long they will issue a policy for.
-
What happens when construction is finished?
Once construction is complete and the property is ready for occupancy, the builders risk policy is typically replaced with a standard homeowners insurance policy or landlord insurance policy, depending on how the property will be used.
Insurance Blog for Construction, Real Estate and Business
Why Ontario Landlords Can’t Have a No Pets Clause in Ontario
How to Handle Vacant Properties: Insurance Tips for Landlords and Homeowners
Difference Between Home Insurance & Rental Property Insurance
City of Toronto Approves Implementation of Vacant Home Tax
10 Tips to Protect Your Home from Water Damage